Authentication failures are fraud prevention failures
When authentication and fraud prevention operate in silos, account takeover attacks slip through. Here's what unified detection actually looks like.
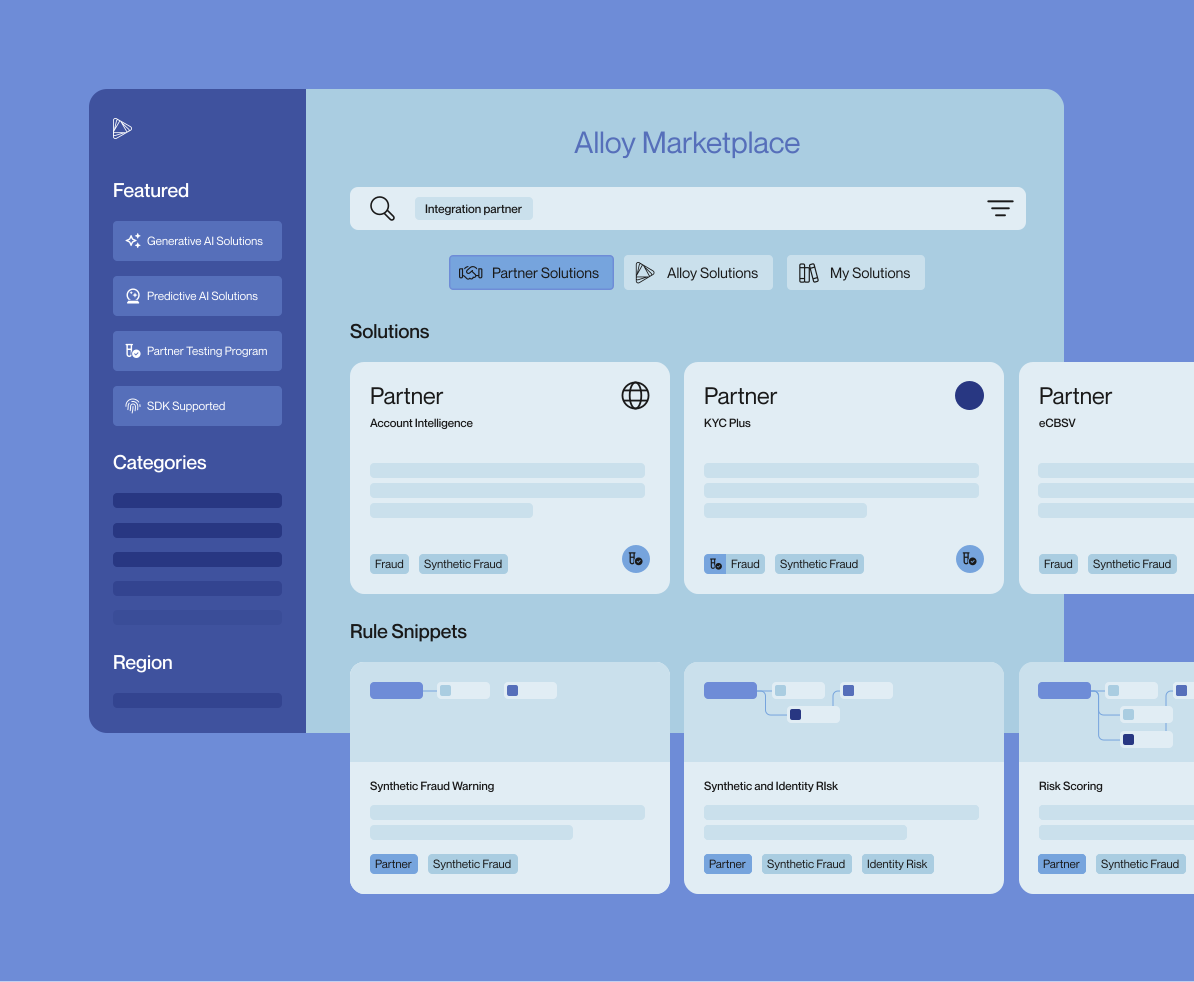
Alloy Marketplace unites 270+ partner solutions and a new library of pre-built decisioning logic in one dashboard. Discover, test, and deploy from one place.
Why spend time on tedious manual reviews when AI can do it for you? Learn how agentic AI for KYC and compliance is helping financial orgs optimize efficiency.
7th largest credit union in the U.S. drives growth by keeping members safe
Alloy’s real-time risk assessments helps IncredibleBank create a holistic risk profile for each applicant.
Alloy helps Earnest optimize customer onboarding and underwriting to boost conversion rates
Know Your Agent (KYA) is how financial institutions verify AI agents acting for customers. Learn the core controls and how it differs from KYC.
Learn how actionable AI empowers financial institutions and fintechs to move from detecting fraud to agile prevention.
Banks and fintechs run into challenges that cause customer friction when it comes to AML, KYB, and KYC regulations.
Fraud prevention is no longer a cost center; it’s a product differentiator. Learn how financial institutions and fintechs can build trust, fight AI-driven scams, and drive growth with seamless protection.
Join Alloy and Fintech Takes for a candid discussion on where AI creates real impact — and where the risks are real, too.
See Alloy’s Q4 product updates, from predictive fraud signals and AI-driven decisioning to identity-centric risk assessments and new partner integrations.
Strengthen your approach to authentication with an identity verification layer. Alloy works with your CIAM to prevent fraud risk.
LONDON, 21 January, 2026 – Alloy, an identity orchestration platform provider serving over 700 financial institutions and fintechs globally, has today announced the launch of its first perpetual Know Your Business (pKYB) and Customer Risk Assessment (CRA) orchestration solution in the UK and Europe. This launch follows the European launch of Alloy’s perpetual KYC (pKYC) solution in Autumn 2025.Alloy’s pKYB solution enables UK and European banks, fintechs, and payments companies to move beyond static, point-in-time KYB by automatically re-running checks and re-assessing risk when meaningful business and ownership changes occur (for instance, registry updates, watchlist hits, and event-driven risk signals). The solution is bolstered by Alloy’s AI Assistant, which helps further automate the perpetual KYB process by conducting open-ended web research to corroborate business and ownership changes and by running the Enhanced Due Diligence (EDD) review for businesses that change from low to high risk post-onboarding.This helps compliance and risk teams cut down on hours of manual work while improving straight-through-processing (STP) rates.“Through deep conversations with our UK and European clients, it became clear that static, point-in-time KYB was no longer sufficient,” says Grace Liu, Senior Product Director at Alloy. “We took what we learned, evaluated how the pKYB ecosystem was evolving, and built on our pKYC foundation to move quickly toward a proactive, event-driven future — one our clients are genuinely excited about and that Alloy is uniquely positioned to deliver.”For financial institutions operating in the UK and across Europe, expansion into new territories is often integral to their sustained business growth strategies. As that expansion happens, business risk becomes harder to manage: corporate entities evolve, beneficial owners change, and regulatory expectations continue to rise. Yet many business monitoring programmes still rely on heavily manual workflows in which analysts must sift through high volumes of updates, interpret changes, and apply bespoke policies across markets. Rising regulatory expectations are also amplifying the need for more UK and European fintechs and financial institutions to automate their business monitoring. Central banks and regulators throughout Europe are increasing the number of regulatory actions they take against neobanks and traditional banks in their jurisdictions for lack of anti-money laundering controls.“Periodic checks alone aren’t enough—they need to be complemented by continuous business monitoring,” Liu continues. “With pKYB, Alloy helps institutions detect, evaluate, and act on changes to business identity, ownership, and risk by automating risk reassessment and escalating only the most critical alerts to analysts. The result is consistent policies across markets and the ability to scale confidently, with a clear, up-to-date understanding of business risk between reviews.”Early UK test users report that Alloy’s pKYB and CRA solution enables them to achieve strong compliance standards far faster than if they were to build an in-house alternative. Rather than investing heavily in their own technology development to get to a baseline level of compliance integrity, Alloy’s solution allows teams the potential to move ahead of competitors without losing development time and/or sinking unnecessary development costs. Alloy’s approach to pKYB is built for multi-market scale and operational efficiency, enabling institutions to:Apply configurable policies by market, product, and entity risk level, supporting consistent decisioning while accommodating local regulatory requirements.Reduce manual workload with smart routing, using filtered, event-triggered Enhanced Due Diligence (EDD) alerts that send only the highest-risk changes to analysts, while lower-risk updates can flow through automated Customer Due Diligence (CDD) processes.Accelerate investigations with AI-assisted workflows, including summaries and recommended next steps to speed review-to-resolution.About AlloyAlloy provides an identity and fraud prevention platform that enables global financial institutions and fintechs to manage identity risk so they can grow with confidence. Over 700 of the world’s largest financial institutions and fintechs turn to Alloy’s end-to-end platform to access actionable intelligence and the broadest network of data sources across the industry, as well as stay ahead of fraud, credit, and compliance risks. Founded in 2015, Alloy is powering the delivery of great financial products to more customers around the world.
In this eBook, we explore how using multiple data source providers in your identity verification process can not only help you mitigate fraud risks, but also bring on more good customers.
Learn how perpetual KYB software helps financial institutions continuously verify business identity, ownership, and risk to support AML and fraud prevention.
Alloy’s native AI agents bring agentic AI to risk decisioning with full context, auditability, and enterprise-grade reliability.
Sara Seguin shares insights from Alloy's 2026 State of Fraud Report, from rising threats to using fraud prevention as a competitive advantage.
Embedded finance shook up everyone, from banks to BaaS providers and end-brands. Learn how to leverage embedded finance for sustainable growth using our guide.
Subscribe to our blog for the latest posts, resources, and events for all things banking and fintech.
PLANO, TX —Dec. 18, 2025 — MANTL, an Alkami solution team and leading provider of loan and deposit account opening technology, and Alloy, a leading identity and fraud prevention platform provider, today announced that their partnership has processed more than 2 million deposit applications, achieving an average automated application decision rate exceeding 80%. The partnership now supports over 150 shared customers, delivering a seamless, end-to-end account opening and risk management workflow that helps financial institutions increase conversion rates, reduce fraud, and scale their operations.“Within a year of overhauling our account opening process with MANTL and fully leveraging the MANTL–Alloy integration, Ascend Bank reduced new account fraud losses by $165,000,” said Alex Sulpasso, executive vice president and chief operating officer at Ascend Bank in Connecticut. “The integrated solution has also transformed how our Risk and BSA teams operate, giving them real-time visibility into fraud and identity risk and automating critical KYC and KYB workflows. It’s dramatically improved both our operational efficiency and our ability to onboard customers with confidence.”The longstanding partnership was built on a shared vision: enabling financial institutions to grow efficiently while managing identity and fraud risk with confidence. MANTL provides a configurable, streamlined omnichannel account opening experience, while Alloy orchestrates and validates identity, fraud, and compliance data behind the scenes. Together, the integration has fundamentally changed how banks and credit unions onboard customers and members, setting an industry standard for digital account opening and risk management.“What makes this partnership so effective is the depth and maturity of our integration, our shared commitment to innovation, and our clear alignment on both product strategy and customer and member outcomes,” said Benjamin Conant, chief product officer, Alkami. “MANTL and Alloy were founded within a few years of each other, and we’ve grown together as strategic partners, helping the industry rethink what growth can look like, all while raising the bar for fraud prevention both online and in-branch. We’re excited for the next 2 million applications to be processed as we continue expanding into additional use cases that will further strengthen the joint value we deliver to financial institutions and their account holders.”“Our partnership with MANTL shows that strong fraud prevention can actively fuel business growth,” said Tommy Nicholas, co-founder and chief executive officer of Alloy. “By giving our joint clients a complete view of customer identities, we’re helping them stay ahead of fraud, unlock more opportunities to serve legitimate customers, and deliver a better experience.”Both companies remain focused on helping financial institutions modernize and streamline operational workflows, while addressing increasingly complex identity and risk challenges within digital banking. To learn how MANTL and Alloy can transform your onboarding and account opening process, empowering your team, or to schedule a demo, click here.About MANTLMANTL is an Alkami solution team that offers unified account origination technology, empowering banks and credit unions to open loan and deposit accounts seamlessly on any banking channel in real time. MANTL Deposit Origination is among the fastest and most performant solutions on the market; consumers can open a new deposit account in under five minutes, businesses can open a new deposit account in under 10 minutes, and MANTL customers raise billions in core deposits. MANTL Loan Origination simplifies each step in the loan process, automating up to 100% of loan application decisions to ensure an intuitive, feature-rich experience from personal loans to business financing. Founded in 2016, MANTL was acquired in March 2025 by Alkami Technology, Inc. (Nasdaq: ALKT), a digital sales and service platform provider for financial institutions in the U.S. For more information, visit mantl.com or follow MANTL on LinkedIn.About AlloyAlloy provides an identity and fraud prevention platform that enables global financial institutions and fintechs to manage identity risk so they can grow with confidence. Over 700 of the world's largest financial institutions and fintechs turn to Alloy's end-to-end platform to access actionable intelligence and the broadest network of data sources across the industry, as well as stay ahead of fraud, credit, and compliance risks. Founded in 2015, Alloy is powering the delivery of great financial products to more customers around the world. Learn more at alloy.com.
Perpetual KYC uses automated KYC verification to continuously monitor customers, keeping risk profiles current and maintaining compliance with regulations.
By rethinking customer onboarding with Clutch and Alloy, Launch Credit Union unlocked rapid growth and friction-right fraud protection
To support sustainable, scalable growth, Skyla implemented Clutch for digital account opening and Alloy for identity and fraud decisioning.
Catch a practical discussion between Alloy and Santander on how modernizing authentication can enable safe growth in a zero-trust world.
Join Alloy and Bank Director for an in-depth look at how institutions are confronting AI-enabled attacks and implications for the year ahead.
Tune in as Alloy and Ally Bank take an in-depth look at how the fraud landscape is shifting and implications for the year ahead.
NEW YORK, December 9, 2025 – Alloy today announced the release of its annual State of Fraud Report, a detailed look at shifting trends in financial fraud, based on a survey of over 500 senior-level fraud decision-makers working at banks, credit unions, and fintechs in the U.S. This year, fraud professionals overwhelmingly agree (67%) that fraud events continue to rise, driven by bad actors’ use of new tools like generative AI to carry out their attacks on a greater scale.The impact of these fraud events also expanded in the last twelve months. Decision makers ranked losses due to goodwill credit to clients as the top reported consequence of fraud over the past year, and over one in five organizations (22%) reported losing over $5M in direct fraud losses. The true cost of fraud is likely even higher, as the majority (63%) of those surveyed reported that fraud losses are underreported. “One of the biggest changes to the fraud landscape has been the adoption of AI to combat fraud,” said Alloy Co-Founder and CEO Tommy Nicholas. “Bad actors are more sophisticated than ever, making the use of tools like AI table stakes in fraud prevention. In 2026, the distinction won’t be who uses AI; it will be how—specifically how to anticipate attacks and identify risk the moment it enters the system.”Other key findings include:AI is a driving factor in the rise of fraud: 91% of decision makers reported that more financial crimes are being committed with AI technology.In response, 82% of organizations stated they’ve increased their investment in AI-driven fraud prevention technologies.Synthetic identity fraud is the most common type of fraud by case volume:44% of respondents ranked synthetic identity fraud as the top fraud type tracked in their organization.89% also ranked synthetic identity creation as the most concerning fraud tactic when it comes to tactics that are evolving with AI.In addition to third-party fraud, first-party fraud and scams are rising threats for financial organizations:Fraud professionals attributed 36% of fraud events to organized fraud rings, 29% to customers intentionally stealing money from their financial institutions, and 29% to customers who were coerced or scammed.Online and mobile banking continue to be the most frequently targeted channels for fraud, although the frequency at which they are targeted shifted:Fraud in mobile banking rose by 7% year over year. Meanwhile, fraud in online banking saw a drop of 16%. Fraud prevention requires significant investment from financial institutions, but has a positive ROI:27% of organizations spend greater than 15% of their annual budget on fraud prevention; meanwhile,92% of decision makers report that their organization's fraud prevention efforts have helped them grow the business, and 84% reported that fraud prevention has resulted in higher rates of customer satisfaction.“This year’s report is a strong reminder that where there is money, there are bad actors looking for vulnerabilities to access it; and that those bad actors now have better tools than ever before,” Nicholas said. “But it also illustrates how far the industry has advanced when it comes to managing those risks. Most organizations are no longer looking at fraud as a threat, they are also considering how managing it can unlock their goals to provide a better experience, offer more products and increase customer loyalty.”The 2026 State of Fraud Report is based on responses from over 500 decision-makers working in a director-level role or higher in the financial services industry across the enterprise banking, regional and community banking, credit union, and fintech sectors. The survey was conducted on behalf of Alloy by The Harris Poll, a global consulting and market research firm.About AlloyAlloy provides an identity and fraud prevention platform that enables global financial institutions and fintechs to manage identity risk so they can grow with confidence. Over 700 of the world's largest financial institutions and fintechs turn to Alloy's end-to-end platform to access actionable intelligence and the broadest network of data sources across the industry, as well as stay ahead of fraud, credit, and compliance risks. Founded in 2015, Alloy is powering the delivery of great financial products to more customers around the world. Learn more at alloy.com.
Get 2026 fraud trends and statistics for financial institutions and fintechs, and benchmark your fraud strategy to elevate your defenses.
Learn how financial institutions can predict and prevent seasonal fraud spikes. Explore tax season scams, holiday surges, and how actionable AI strengthens defenses.
Fintechs: What's the difference between KYC and KYB verification? How do KYC checks work? Alloy clarifies essential identity verification definitions.
Finding the right sponsor bank is key to fintech success. Learn what questions to ask around regulatory posture, compliance maturity, and scalability.
Discover how stablecoin regulation and global fintech adoption are reshaping payments. See how Alloy helps institutions and fintechs manage on-chain and off-chain risk.