Authentication failures are fraud prevention failures
When authentication and fraud prevention operate in silos, account takeover attacks slip through. Here's what unified detection actually looks like.
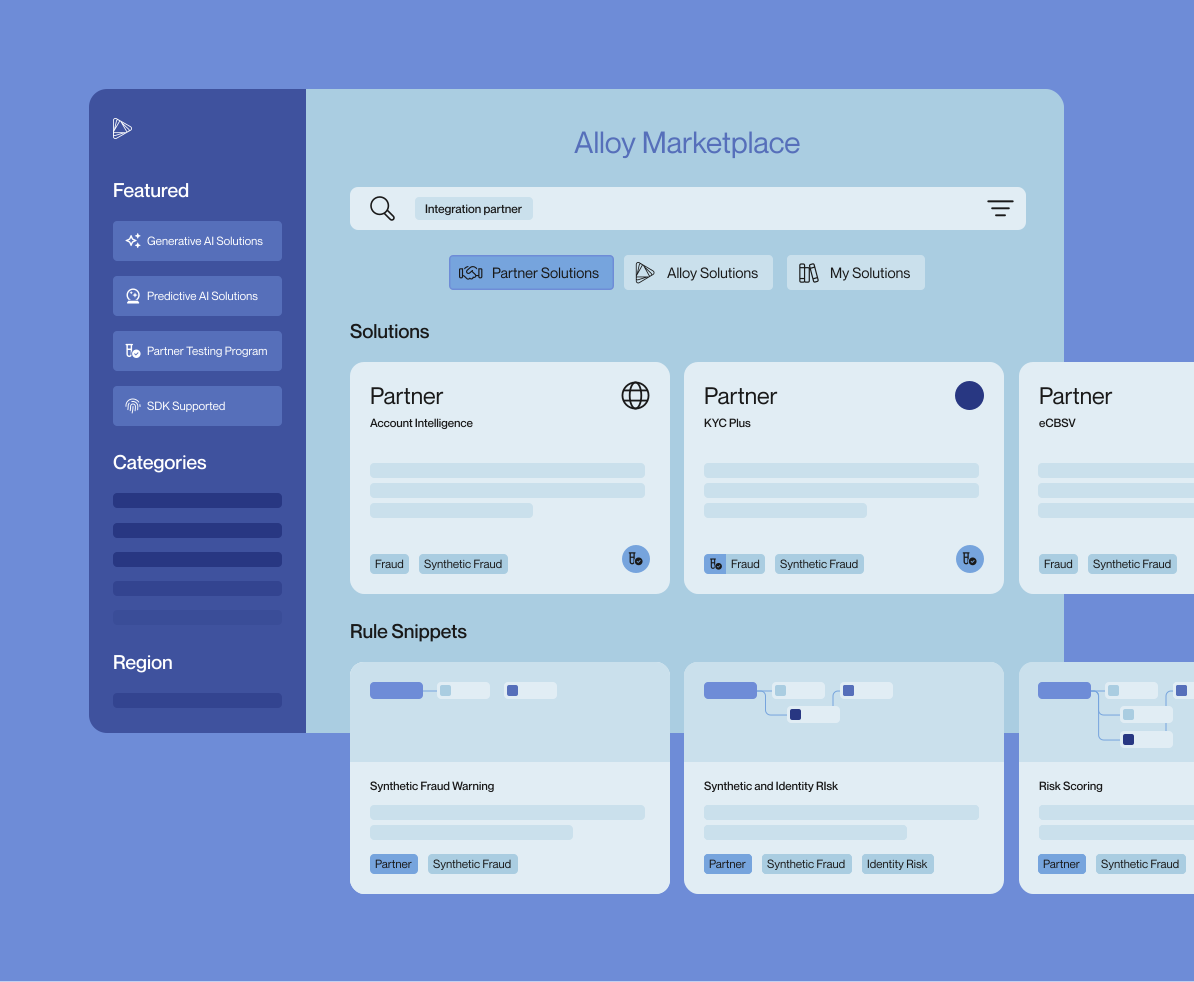
Alloy Marketplace unites 270+ partner solutions and a new library of pre-built decisioning logic in one dashboard. Discover, test, and deploy from one place.
Why spend time on tedious manual reviews when AI can do it for you? Learn how agentic AI for KYC and compliance is helping financial orgs optimize efficiency.
7th largest credit union in the U.S. drives growth by keeping members safe
Alloy’s real-time risk assessments helps IncredibleBank create a holistic risk profile for each applicant.
Alloy helps Earnest optimize customer onboarding and underwriting to boost conversion rates
Know Your Agent (KYA) is how financial institutions verify AI agents acting for customers. Learn the core controls and how it differs from KYC.
Learn how actionable AI empowers financial institutions and fintechs to move from detecting fraud to agile prevention.
Banks and fintechs run into challenges that cause customer friction when it comes to AML, KYB, and KYC regulations.
How do you define “fraudster”? From ATO to wire fraud, Alloy’s ongoing list of financial fraud types and definitions keeps you in the know.
Credit underwriting is a tedious process. Amidst changing market demands and increasing customer expectations, Alloy helps you reimagine it.
Alloy and Equifax team up to explore the benefits of alternative data.
An identity and fraud prevention platform is an end-to-end platform for managing fraud, credit, and compliance risk, providing the clearest picture of customers throughout the entire customer lifecycle.
Learn which factors lead to bust-out fraud, and how to stop it. Protect your bank, fintech, or credit union from this sudden financial threat.
Alloy enriched existing capabilities to offer a more comprehensive testing hub that allows clients to test new policies or changes to their decisioning logic and see projected outcomes, easing the pressure of making changes and going live. This type of agility is critical in an era of growing fraud.
Alloy's Product Director, Grace Liu, takes you through the thought process and development of one of our most exciting software features: Journeys.
This guide will take you through the things you should consider to create a digital strategy you can bank on.
Alloy helps Earnest optimize customer onboarding and underwriting to boost conversion rates
We interview Navan's Head of Risk Management, Rajat Bhatia about the biggest misconceptions about what it means to manage risk at a fast-growing organization.
Take a dynamic approach to customer retention. With Alloy Ongoing Monitoring, you can remarket to your existing customers and extend highly personalized credit offerings.
Explore Alloy's best practices for credit risk management to adeptly navigate through economic uncertainties, mitigate risks, and ensure financial resilience.
Banks and fintechs must move faster and meet diverse borrowers' needs, but complex credit underwriting workflows present significant challenges. An Identity Risk Solution can help.
Digital ID verification is central to seamless onboarding processes and fraud prevention. Learn how Alloy can improve the identity verification process.
Banks and fintechs need faster loan origination processes, but different types of credit risk complicate underwriting workflows and create more complexity. An Identity Risk Solution can help.
What started as a simple piece of technology has evolved to help banks and fintechs stay ahead of ever-changing fraud risks.
You don’t want to get caught in a fraud attack and then have to scramble to figure out how to respond, build new workflows and integrate with new data providers. We share some tips on how you can stay one step ahead of fraudsters.
Lending decisions have relied heavily on credit scores since they were first introduced in the late-1950s. However, some FIs have recently started incorporating alternative sources of data into their lending decisions. After more than 60 years of trusting credit scores, what is prompting our industry to rethink them?
Many members of the underbanked population have no or thin credit files — which, in a classic case of what comes first, the chicken or the egg — makes it even harder for them to acquire a credit card. But how can organizations safely verify and underwrite these populations? I asked experts from Alloy, Equifax, Nova Credit, Zest AI, and Ocrolus to find out.
KYC, KYB, and AML laws require financial institutions to verify a company’s (and its beneficial owners’) identity before offering the business financial services or products. We break down the nuances of onboarding sole props vs. LLCs.
Framing Fintech is a blog series where our GM of Fintech, Charley Ma, interviews leaders in the industry. In part two of Charley Ma's conversation with Aaron Frank, Aaron unpacks the key customer lifecycle events for credit cards, areas where credit card companies get it wrong, and types of fraud that credit card companies should be looking out for.
In the new edition of Framing Fintech, Charley Ma sat down with Aaron Frank to get his advice on how new credit card startups should approach launching a credit product.
Customers want more personalized experiences. How does digital banking stack up? Gartner Peer Insights and Alloy surveyed 100 bank leaders to understand what their organizations are doing to provide a personalized and digital customer experience.
Alloy's SDK offers a codeless solution for customer onboarding and multi-vendor management. Integrate once and iterate endlessly without wasting engineering resources.