Authentication failures are fraud prevention failures
When authentication and fraud prevention operate in silos, account takeover attacks slip through. Here's what unified detection actually looks like.
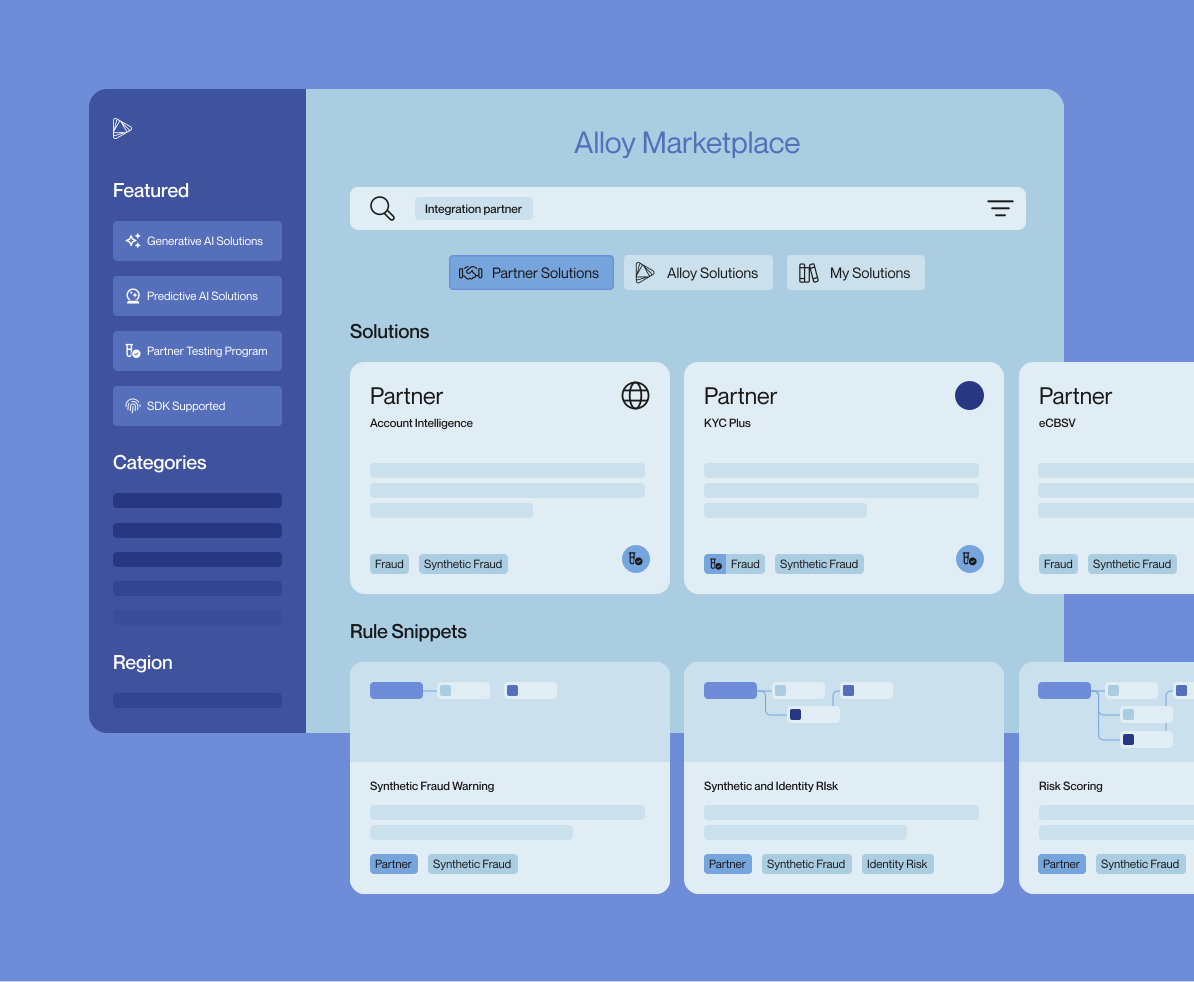
Alloy Marketplace unites 270+ partner solutions and a new library of pre-built decisioning logic in one dashboard. Discover, test, and deploy from one place.
Why spend time on tedious manual reviews when AI can do it for you? Learn how agentic AI for KYC and compliance is helping financial orgs optimize efficiency.
7th largest credit union in the U.S. drives growth by keeping members safe
Alloy’s real-time risk assessments helps IncredibleBank create a holistic risk profile for each applicant.
Alloy helps Earnest optimize customer onboarding and underwriting to boost conversion rates
Know Your Agent (KYA) is how financial institutions verify AI agents acting for customers. Learn the core controls and how it differs from KYC.
Learn how actionable AI empowers financial institutions and fintechs to move from detecting fraud to agile prevention.
Banks and fintechs run into challenges that cause customer friction when it comes to AML, KYB, and KYC regulations.
PLANO, TX —Dec. 18, 2025 — MANTL, an Alkami solution team and leading provider of loan and deposit account opening technology, and Alloy, a leading identity and fraud prevention platform provider, today announced that their partnership has processed more than 2 million deposit applications, achieving an average automated application decision rate exceeding 80%. The partnership now supports over 150 shared customers, delivering a seamless, end-to-end account opening and risk management workflow that helps financial institutions increase conversion rates, reduce fraud, and scale their operations.“Within a year of overhauling our account opening process with MANTL and fully leveraging the MANTL–Alloy integration, Ascend Bank reduced new account fraud losses by $165,000,” said Alex Sulpasso, executive vice president and chief operating officer at Ascend Bank in Connecticut. “The integrated solution has also transformed how our Risk and BSA teams operate, giving them real-time visibility into fraud and identity risk and automating critical KYC and KYB workflows. It’s dramatically improved both our operational efficiency and our ability to onboard customers with confidence.”The longstanding partnership was built on a shared vision: enabling financial institutions to grow efficiently while managing identity and fraud risk with confidence. MANTL provides a configurable, streamlined omnichannel account opening experience, while Alloy orchestrates and validates identity, fraud, and compliance data behind the scenes. Together, the integration has fundamentally changed how banks and credit unions onboard customers and members, setting an industry standard for digital account opening and risk management.“What makes this partnership so effective is the depth and maturity of our integration, our shared commitment to innovation, and our clear alignment on both product strategy and customer and member outcomes,” said Benjamin Conant, chief product officer, Alkami. “MANTL and Alloy were founded within a few years of each other, and we’ve grown together as strategic partners, helping the industry rethink what growth can look like, all while raising the bar for fraud prevention both online and in-branch. We’re excited for the next 2 million applications to be processed as we continue expanding into additional use cases that will further strengthen the joint value we deliver to financial institutions and their account holders.”“Our partnership with MANTL shows that strong fraud prevention can actively fuel business growth,” said Tommy Nicholas, co-founder and chief executive officer of Alloy. “By giving our joint clients a complete view of customer identities, we’re helping them stay ahead of fraud, unlock more opportunities to serve legitimate customers, and deliver a better experience.”Both companies remain focused on helping financial institutions modernize and streamline operational workflows, while addressing increasingly complex identity and risk challenges within digital banking. To learn how MANTL and Alloy can transform your onboarding and account opening process, empowering your team, or to schedule a demo, click here.About MANTLMANTL is an Alkami solution team that offers unified account origination technology, empowering banks and credit unions to open loan and deposit accounts seamlessly on any banking channel in real time. MANTL Deposit Origination is among the fastest and most performant solutions on the market; consumers can open a new deposit account in under five minutes, businesses can open a new deposit account in under 10 minutes, and MANTL customers raise billions in core deposits. MANTL Loan Origination simplifies each step in the loan process, automating up to 100% of loan application decisions to ensure an intuitive, feature-rich experience from personal loans to business financing. Founded in 2016, MANTL was acquired in March 2025 by Alkami Technology, Inc. (Nasdaq: ALKT), a digital sales and service platform provider for financial institutions in the U.S. For more information, visit mantl.com or follow MANTL on LinkedIn.About AlloyAlloy provides an identity and fraud prevention platform that enables global financial institutions and fintechs to manage identity risk so they can grow with confidence. Over 700 of the world's largest financial institutions and fintechs turn to Alloy's end-to-end platform to access actionable intelligence and the broadest network of data sources across the industry, as well as stay ahead of fraud, credit, and compliance risks. Founded in 2015, Alloy is powering the delivery of great financial products to more customers around the world. Learn more at alloy.com.
Discover Alloy's Partner Center — a dynamic dashboard offering 250+ AI-powered data solutions to help financial institutions fight fraud and manage identity risk.
NEW YORK (AUGUST 20, 2025) – Alloy, a leading identity and fraud prevention platform provider, has announced a new global partnership with Mastercard to launch an enhanced customer onboarding solution for financial institutions and fintechs. The new Mastercard Alloy joint onboarding solution will leverage identity verification and open finance to streamline the end-to-end onboarding process while combatting fraud.According to Alloy’s 2025 State of Fraud Report, fraud rates continue to rise, with 60% of financial institutions and fintechs reporting an increase in 2024. As a result, 93% of financial organizations reported plans to invest in ongoing fraud prevention measures in 2025, with 64% planning to implement an identity risk solution.The Mastercard Alloy joint onboarding solution provides a consistent identity risk strategy and onboarding experience across channels. Alloy intends to leverage Mastercard’s best-in-class global digital identity verification capabilities and suite of open finance-powered account opening solutions to help financial institutions and fintechs manage fraud and identity risk and secure account funding throughout the customer lifecycle. Mastercard products will be integrated and pre-configured in Alloy for seamless deployment. In addition to pre-built integrations to Mastercard products, customers will receive access to over 200 risk and identity solutions available through Alloy, helping to improve customer conversion rates, reducing manual reviews, and ensuring comprehensive end-to-end coverage. “Fraud continues to be a significant challenge for financial institutions and consumers alike, underscoring the urgent need for robust fraud prevention measures,” said Dennis Gamiello, EVP, Global Head of Identity at Mastercard. “This joint onboarding solution will be a game-changer in the fight to reduce fraud and deliver a seamless and secure customer experience.”“Successful fraud prevention starts with a holistic approach to understanding identity. Our partnership with Mastercard will allow more financial institutions and fintechs to evaluate customer identities holistically. The end result for those companies will be a better digital experience and less fraud risk, allowing their businesses to grow effectively,” said Parilee Wang, Chief Product Officer at Alloy.To learn more about Alloy, visit http://alloy.comAbout AlloyAlloy provides an identity and fraud prevention platform that enables global financial institutions and fintechs to manage identity risk so they can grow with confidence. Over 700 of the world's largest financial institutions and fintechs turn to Alloy's end-to-end platform to access actionable intelligence and the broadest network of data sources across the industry, as well as stay ahead of fraud, credit, and compliance risks. Founded in 2015, Alloy is powering the delivery of great financial products to more customers around the world.
Consumers Credit Union partners with Alloy to prevent fraud and improve their omnichannel member experience
NEW YORK, July 16, 2025 – Alloy, a leading identity and fraud prevention platform provider, has been recognized on CNBC‘s World’s Top Fintech Companies 2025, a listing of the top 250 fintech companies globally ranked by CNBC together with market research firm Statista. This is Alloy’s second time to be named to the prestigious list. “Winning this award is an honor because it speaks to our strength across multiple vectors including our platform, our client success and support teams, and our culture,” said Tommy Nicholas, CEO and Co-founder at Alloy. “We’re looking forward to continuing the momentum as we further grow our team and simultaneously help our clients grow their businesses.”Alloy was founded in 2015 to help solve the identity risk problem for companies that offer financial products by enabling them to outpace fraud and confidently serve more people around the world. Over 700 of the world’s largest financial institutions and fintechs turn to Alloy to take control of fraud, credit, and compliance risk, and grow with the clearest picture of their customers. Alloy’s identity and fraud prevention platform provides access to over 250 partner solutions to help clients make decisions about their customers in real-time. “Alloy has spent the last decade building a product and team trusted by some of the largest fintechs and financial institutions in the world,” said Charles Birnbaum, Partner at Bessemer Venture Partners. “Along the way, they’ve stayed true to fostering a culture of collaboration that continues to set them apart as a best place to work in fintech.”Headquartered in New York, NY, Alloy is comprised of over 280 employees and has been recognized as a Best Workplace by Forbes, Inc., American Banker, and more. Interested applicants can apply for open roles at https://www.alloy.com/about/jobs. About AlloyAlloy provides an identity and fraud prevention platform that enables global financial institutions and fintechs to manage identity risk so they can grow with confidence. Over 700 of the world’s largest financial institutions and fintechs turn to Alloy’s end-to-end platform to access actionable intelligence and the broadest network of data sources across the industry, as well as stay ahead of fraud, credit, and compliance risks. Founded in 2015, Alloy is powering the delivery of great financial products to more customers around the world. Learn more at alloy.com.
London, 18 June 2025 -- IG Group (“IG”), the FTSE 250 online trading company, has partnered with Alloy, a leading identity and fraud prevention platform provider. The partnership enables IG to better achieve full regulatory compliance without impinging on the company’s capacity to provide a seamless customer experience and hit ambitious business growth objectives. The UK financial services industry has developed one of the most rigorous and demanding regulatory regimes globally. Meeting compliance standards is critical to the success of any UK financial services or fintech company. Asked to name the most concerning consequences of fraud in Alloy’s recently published State of UK Fraud Report, almost all C-suite leaders at UK fintechs put satisfying regulatory requirements and mitigating reputational damage at the top of the list.* On top of this pressure to remain compliant, UK fintechs and banks also face pressure to grow. Many businesses operate on outdated, internally-built tech stacks that are too rigid to adapt to evolving demands. At the point of onboarding or verifying customers, the collection and verification of documentation is often managed manually, resulting in fragmented workflows, poor data visibility and a high volume of referrals to KYC analysts for further manual inspection. These delays and hurdles typically result in lower than desired STPs (straight through processing rates), which in turn lead to higher lead times to account activation and higher dropout rates in prospective clients. Alloy’s industry research indicates that this complexity is heightened in businesses like IG that serve customers in multiple markets globally and are processing multimillion pound transactions. Without automated workflows that enable perpetual KYC, unnecessary friction and delays can be passed onto customers. William Mead, Head of Operations at IG Group, comments: “Integrating Alloy’s identity and fraud prevention platform into our risk management processes is transforming perpetual KYC from a conceptual ideal to a real-life, proven way of operating that increases automation and efficiency, and reduces risk and development burden. “From the outset, Alloy’s UK team fundamentally appreciated the drain on capacity and resources that continual ID verification creates without the right technology in place. Alloy’s automated verification and monitoring tools help us refocus our attention and efforts to deliver the sort of user experience an IG customer expects from us. By continually ensuring we know who our customers are in accordance with expanding regulatory rules, the experience we can provide feels less intrusive, less onerous and more streamlined.” By leveraging Alloy, IG has been able to develop a dynamic and holistic approach to risk management through the client lifecycle from onboarding to in-life. This approach reduces the potential for regulatory risk, alleviates the need for remediation efforts after risks are exposed, and improves customer conversion and retention. At the same time, Alloy enables IG to consolidate operational workflows in all jurisdictions and orchestrate multiple data signals for due diligence flows based on risk level and geographic requirements, which results in far more automated processes and fewer manual activities. Since integration, IG has experienced a significant increase in automated activations. Most of the time previously spent handling remediation efforts after risks were retrospectively exposed is deployed elsewhere on activities like proactively improving internal processes and enhancing the customer journey.James Baston-Pitt, Alloy’s Head of Growth UK, EMEA and APAC, adds: “IG is an exceptional company that has been focused and collaborative in making bold transformations to their customer decision-making and in-life processes. Balancing the importance of robust, compliant, and seamless experiences globally involves fine-tuning customer journeys to maximise automation in both core and expansion markets. We are very excited about what we have achieved together so far.”Notes to Editors * 93% of UK fintech C-Suite leaders rank regulatory penalties and reputational damage as the most concerning consequences of fraud - Alloy State of UK Fraud Report, March 2025About IG GroupIG Group (LSEG:IGG) provides online trading platforms and educational resources to empower ambitious clients around the globe. Headquartered in the UK, IG Group is a FTSE 250 company that offers clients access to ~19,000 financial markets worldwide. www.iggroup.com About AlloyAlloy provides an identity and fraud prevention platform that enables global financial institutions and fintechs to manage identity risk so they can grow with confidence. Over 700 of the world’s largest financial institutions and fintechs turn to Alloy’s end-to-end platform to access actionable intelligence and the broadest network of data sources across the industry, as well as stay ahead of fraud, credit, and compliance risks. Founded in 2015, Alloy is powering the delivery of great financial products to more customers around the world. https://www.alloy.com/uk
Discover how Alloy’s annual hackathon drives innovation, boosts productivity, and delivers real value to clients — with past projects like Alloy for Embedded Finance, a testing suite, and internal automation tools.
An identity and fraud prevention platform is an end-to-end platform for managing fraud, credit, and compliance risk, providing the clearest picture of customers throughout the entire customer lifecycle.
NEW YORK, NY (March 24, 2025) -- IncredibleBank, a digital-focused community bank headquartered in Wausau, WI, has partnered with Alloy, a leading identity and fraud prevention platform provider, to provide faster service to improve its account opening process, helping the bank to accelerate growth and reduce manual reviews. "Before Alloy, our account opening platform leveraged a single data source and was completely manual," said Phil Suckow, VP of Innovation at IncredibleBank. "Our application volume varied month-to-month, from a few hundred to a few thousand applications, requiring significant back-end resources during spikes. Now, everything is instant."By leveraging Alloy, IncredibleBank significantly improved the bank's digital onboarding process and overall operational efficiency. Application review time was reduced by 88%, and manual reviews were reduced by 90%. IncredibleBank selected Alloy after evaluating several platforms, citing its robust automation capabilities, user-friendly interface, and proven success in mitigating fraud. Alloy's platform has enabled IncredibleBank to:Reduce new account approval times from 2-5 days to instant decisionsCreate holistic risk profiles for applicants by combining five different data sourcesReallocate a full-time employee from application reviews to sales-focused tasksIdentify and mitigate potentially fraudulent applications more effectively“The move to Alloy was strategic, improving our onboarding customer experience and driving business growth without added risk,” Phil Suckow, VP of Innovation at IncredibleBank added. “We needed a platform to automate KYC, KYB, and fraud at originations at an enterprise level. Alloy met those requirements and allowed us to leverage its platform across various business units.” "We are thrilled to partner with IncredibleBank to enhance their account opening process and drive their growth. Their mission is to grow their customers' entire financial relationship is one we wholeheartedly support and are proud to help the bank as they aim to provide an incredible customer experience," said Jamie Verdi, Head of Client Success at Alloy.To learn more about Alloy, visit http://alloy.com About AlloyAlloy provides an identity and fraud prevention platform that enables global financial institutions and fintechs to manage identity risk so they can grow with confidence. Over 600 of the world's largest financial institutions and fintechs turn to Alloy's end-to-end platform to access actionable intelligence and the broadest network of data sources across the industry, as well as stay ahead of fraud, credit, and compliance risks. Founded in 2015, Alloy is powering the delivery of great financial products to more customers around the world.
London, United Kingdom, March 5, 2025 -- Flagstone, the UK’s largest savings platform*, has partnered with Alloy, a leading identity and fraud prevention platform provider, to deliver a seamless, automated onboarding experience for individual and business customers. The partnership allows Flagstone to approve new applications within seconds, without impinging on the highest standards of security and compliance, and integrate global data partners into a single dashboard.By leveraging Alloy, Flagstone’s enhanced KYC (Know Your Customer) controls ensure that every new client benefits from a streamlined and intuitive onboarding journey without compromising on rigorous verification processes.With £1.1 trillion lost to financial crime annually in the UK**, financial institutions must strike a delicate balance between security and speed. Traditional onboarding processes can be manual, slow and full of friction, discouraging customers from completing applications and leaving firms vulnerable to fraud. The situation is exacerbated by a surge in AI-driven impersonations, deep fakes and organised crime rings. Together these present greater challenges for companies whose duty it is to protect themselves and their customers from the risk of financial loss. Through its partnership with Alloy, Flagstone has automated its onboarding process, reducing friction, improving conversion and pleasing customers, all without compromising security. With Alloy, Flagstone has significantly upgraded from a legacy onboarding process that sometimes took several hours and required manual oversight. Now, Flagstone has vastly increased its average STP (straight through processing rates). As a result, the company can now offer savers access to the UK market’s widest choice of savings products faster than ever before.Francesco Fulcoli, Chief Compliance and Risk Officer at Flagstone, comments: “Alloy fully understands our ambition to take a data-led approach to analysing our users’ needs and translate that back into the sort of compliant and superior customer experience we want to provide. By digitising our AML/KYC processes with Alloy, we’ve sped up exponentially how quickly savers can begin to enjoy access to hundreds of savings accounts on a single platform. Speed with certainty delights customers, serves our bank partners well, and sets us up for continued market leadership for years to come. Alloy’s automated monitoring and decisioning tools ensure we can meet our regulatory obligations efficiently while offering our customers a fast and secure onboarding experience.”James Baston-Pitt, Alloy’s Head of Growth UK, EMEA and APAC, adds: “Businesses like Flagstone must maintain a constant balance between acting in the best possible interests of their stakeholders while also maintaining a brilliant customer experience. By partnering with Alloy, Flagstone is creating a secure and stable environment in which the business can swiftly verify customer identities without causing unnecessary friction or delays - something that is paramount to the successful operation of this fast-growing, in-demand business. We’re delighted to be the engine behind Flagstone’s latest innovation.”Founded in 2013, Flagstone has grown quickly in the last three years to become the UK’s largest savings platform as more savers than ever turn to cash as a way to maximise the interest earning potential on their money in a low-risk, high-return way. Today Flagstone handles around £16 billion in assets on behalf of its individual, business and charity customers. Flagstone customers generated cumulative returns of more than £500 million on their savings in 2024 through the platform. Flagstone is also the engine behind the savings proposition for over 1000 financial services providers with whom Flagstone has API integrations or partnerships.Founded in 2015, Alloy enables global fintech companies to balance risk with growth as they serve more customers around the world. Some of the world’s fastest-growing fintechs rely on Alloy’s identity and fraud prevention platform to test, launch, and scale new products while maintaining confidence in their customers and the trust of partner banks and regulators. From supporting single-use cases like customer onboarding to powering end-to-end identity risk management, Alloy’s configurable solutions for fraud and compliance risk, dedicated expert guidance, and extensive ecosystem of data partners enable fintechs to future-proof their growth.This announcement follows the recent news that Flagstone has recorded record growth, including a 46% increase in revenue to £55 million and a 49% rise in Assets under Administration (AuA) in the twelve months to 31 December 2024.* Based on number of banks on panel and savings accounts on platform** UK Finance Annual Fraud Report 2024About FlagstoneFlagstone is a fintech company located in London that’s recreating how people grow their money. Since 2015, Flagstone’s group assets under administration stand at around £16 billion and it has become the UK’s largest savings platform by the number of banks and savings accounts on its panel. Flagstone customers can gain access to over 220 savings accounts from 66 of the UK’s leading cash savings providers, from the largest incumbent banks to challengers. Flagstone’s total AUA is currently increasing by more than £1 billion per quarter as more customers look to maximise the interest earning potential while minimising risk. Originally created as a platform for individual savers to access and maintain multiple cash savings accounts in one single place, today Flagstone provides white-label and API-integrated capabilities for businesses to offer their own customers easy-to-use, adaptable and competitive savings options. Flagstone partners with many of the UK’s leading wealth management firms including St. James’s Place, and powers a range of savings products at financial services providers including Saga and Revolut.Flagstone Group Ltd is authorised by the Financial Conduct Authority (reference number 605504) under the Payment Service Regulations 2017 for the provision of payment services. www.flagstoneim.com About AlloyAlloy provides an identity and fraud prevention platform that enables global financial institutions and fintechs to manage identity risk so they can grow with confidence. Over 600 of the world’s largest financial institutions and fintechs turn to Alloy’s end-to-end platform to access actionable intelligence and the broadest network of data sources across the industry, as well as stay ahead of fraud, credit, and compliance risks. Founded in 2015, Alloy is powering the delivery of great financial products to more customers around the world.https://www.alloy.com/uk
2024 was a wild ride. Let’s take a look back at the past year.
Most fraud prevention models no longer keep up with current threats because they focus on transactions instead of identity.
Alloy’s real-time risk assessments helps IncredibleBank create a holistic risk profile for each applicant.
Discover how Alloy and CLEAR's partnership streamlines onboarding, improves security, and enhances the customer experience for financial services.
We’re excited to join the celebration of International Credit Union Day. Learn how Alloy helps credit unions stay compliant and fight fraud.
Alloy enriched existing capabilities to offer a more comprehensive testing hub that allows clients to test new policies or changes to their decisioning logic and see projected outcomes, easing the pressure of making changes and going live. This type of agility is critical in an era of growing fraud.
NEW YORK, October 3, 2024 -- Sonovate, the leading provider of embedded finance and payment solutions for the contingent workforce, today announced that it is implementing Alloy’s identity risk solution to better prevent fraud while also fueling growth.Alloy helps solve the identity risk problem for companies that offer financial products by enabling them to outpace fraud and confidently serve more people around the world. Over 600 banks and fintechs in the US, UK, and beyond turn to Alloy to grow with a clearer picture of their customers. Sonovate will use Alloy’s end-to-end identity risk management platform to stay ahead of rising fraud trends in the UK. A report from UK Finance found that £1.17 billion was lost to financial criminals in 2023. New technologies like generative AI have given bad actors more sophisticated tools to attack financial institutions. With Alloy, Sonovate is poised to stay ahead of this fraud risk while ensuring that genuine customers can efficiently access the company’s products and services.“With its network of data sources, Alloy gives us the power to protect our business and customers from financial crime and the flexibility to make adjustments as needed as our business scales,” said Tom Wilson, Global Head of Risk and Compliance at Sonovate. “We are excited for this next step in our global growth.”Since it was founded in 2014, Sonovate has funded nearly £6 billion ($8 billion) of invoices, supporting 3,300 businesses and 50,000 workers in 44 countries. In pursuit of the company’s global growth, Sonovate recently opened its first overseas office in Amsterdam and announced significant enhancements to its funding technology platform to better serve large, multinational recruitment businesses. Sonovate joins a growing list of UK-based banks and fintechs that use Alloy to solve for identity risk, including Liberis and Flagstone. “We’re excited to support Sonovate in their mission to empower recruitment and consultancy businesses with tailored financial solutions,” said James Baston-Pitt, Head of UK and EMEA at Alloy. “Risk management has always been a core part of Sonovate’s business, and with Alloy, the company will continue to evolve to address growing fraud threats.”About SonovateSonovate is the leading provider of embedded finance and payment solutions for the workforce. Its finance and technology services cater to recruitment businesses, consultancies, and labour marketplaces who place contractors and freelancers around the world. Sonovate’s platform and expert service deliver swift credit decisions, same-day funding, credit insurance and collection services as well as timesheet and workflow automation, empowering companies to concentrate on expanding their business, confident that processes and funds are in place to help meet payment deadlines. Since it was founded in 2014, Sonovate has funded nearly £6 billion ($8 billion) of invoices, supporting 3,300 businesses and 50,000 workers in 44 countries.About AlloyAlloy helps solve the identity risk problem for companies that offer financial products. Over 600 banks, credit unions, and fintechs turn to Alloy’s end-to-end identity risk management platform to take control of fraud, credit, and compliance risks, and grow with confidence. Founded in 2015, Alloy is powering the delivery of great financial products to more customers around the world. Learn more at alloy.com.
BOSTON, October 1, 2024 -- Numerated, the leading AI-driven commercial lending platform, today announced its partnership with Alloy, the identity risk management company trusted by over 600 leading banks, credit unions and fintech companies, to deliver best-in-class fraud checks within commercial lending. This strategic partnership will supercharge Numerated's lending automation capabilities by combining cutting-edge risk management with advanced automation, providing unparalleled security and efficiency to financial institutions.In today’s environment, where fraud is an ever-present threat, this partnership will enable Numerated’s clients to perform robust fraud checks seamlessly within their lending processes. According to Alloy’s State of Fraud Benchmark Report, 100% of fraud decision-makers at banks and fintechs reported experiencing fraud in the last twelve months. Additionally, 96% of these institutions suffered financial losses due to fraud, with 70% reporting losses exceeding $500k during that period. This underscores the critical need for advanced fraud prevention in the financial sector, a need that Alloy’s platform will directly address within Numerated’s commercial lending solutions."Fraud prevention and lending automation are crucial in today's financial landscape," said Dan O’Malley, CEO at Numerated. "By partnering with Alloy, we are ensuring that our platform not only meets but exceeds the expectations of financial institutions looking for secure, scalable lending solutions. This partnership allows us to deliver the best of both worlds—top-tier risk management combined with the efficiency and speed of automation."The partnership will enhance Numerated’s platform in three key ways:Streamlined Onboarding: Automatically prefill customer data to optimize the onboarding process.Strengthened Fraud Prevention: Implement advanced KYC/KYB and AML checks to reduce risk and improve lending performance.Unified Digital Experience: Provide a seamless platform for capturing deposits and offering competitive lending products for SMB and commercial borrowers.“Alloy is excited to partner with Numerated to bring our identity decisioning technology to the commercial lending space,” said Keith Kettell, Chief Revenue Officer at Alloy. “Combining our expertise in fraud prevention with Numerated’s industry-leading lending platform will provide financial institutions with a powerful tool to mitigate risk while automating their lending operations.”This partnership represents a significant step forward in Numerated's mission to modernize business banking. With Alloy's technology, Numerated will continue to lead the industry by offering financial institutions a comprehensive solution that enhances security without sacrificing speed or user experience.About NumeratedNumerated is an AI-driven platform that transforms how financial institutions lend to businesses. By leveraging advanced data and AI, Numerated automates every step of the business lending process, from application to closing, providing lenders with industry-leading efficiency gains. Numerated’s platform is trusted by over 500,000 businesses and 30,000 lenders, processing over $50 billion in loans. Learn more at https://www.numerated.com.About AlloyAlloy helps solve the identity risk problem for companies that offer financial products. Over 600 banks, credit unions, and fintechs turn to Alloy’s end-to-end identity risk management platform to take control of fraud, credit, and compliance risks, and grow with confidence. Founded in 2015, Alloy is powering the delivery of great financial products to more customers around the world. Learn more at alloy.com.
Alloy's Product Director, Grace Liu, takes you through the thought process and development of one of our most exciting software features: Journeys.
NEW YORK, September 24, 2024 -- Meridian Credit Union (“Meridian”), Canada’s second largest credit union, today announced that it is partnering with leading identity risk management company Alloy to provide a better user experience for new and prospective members while also reducing fraud risk. The partnership supports Meridian’s rapid growth, building on its years of commitment to serving Canadians and its base of 380,000 members, by providing the credit union with a centralized platform to manage fraud, credit, and compliance risk. Meridian joins the over 600 leading banks, credit unions, and fintech companies around the globe that rely on Alloy to help solve identity risk."Our members are at the heart of everything we do, so when searching for an identity risk platform, finding the most frictionless option was crucial. Alloy's ability to connect to hundreds of data sources allows us to test and select the vendors that will help create the positive Member experience we strive to deliver while minimizing risk, making it an easy decision for us,” said Matthew Seagrim, Chief Digital and Marketing Officer at Meridian. Alloy’s end-to-end identity risk management platform allows Meridian to identify good customers at origination, while preventing bad actors from gaining access to the organization. Using Alloy’s 200+ data products covering 195 markets—including Canada—Meridian can easily test and make changes to their onboarding policies, optimizing them for growth. Alloy also gives Meridian the ability to perform step-up verification on risky applicants, keeping fraud rates low while cutting back on manual reviews. Alloy’s real-time decisioning capabilities allow Meridian to make faster, more informed decisions, augmenting the credit union’s ability to deliver a personalized, top-notch member experience.“Meridian is well known for providing a high-quality user experience to its members,” said Keith Kettell, Chief Revenue Officer at Alloy. “We’re excited to be a part of that experience by giving Meridian the tools to meet KYC and KYB requirements while also onboarding genuine individuals and businesses efficiently.”Meridian joins a growing number of credit unions that use Alloy to help solve for identity risk, including Navy Federal Credit Union, Suncoast Credit Union, and Mountain America Credit Union. About MeridianMeridian is Ontario’s largest credit union, and one of the largest in Canada. Guided by our purpose, “helping you achieve your best life,” Meridian delivers personal, and wealth financial business solutions to over 380,000 Members. Our bold Meridian for Good strategy is aimed at helping people get access to the money and advice they need; plan for a better future that is clean, resilient, and diverse; and be financially confident. Meridian has two operating subsidiaries: Meridian OneCap Credit Corp (“MOCC”) and motusbank. For more information, please visit: meridiancu.ca.We acknowledge the land on which we operate is the traditional territory of many nations including the Mississaugas of the Credit, the Anishinaabe, the Chippewa, the Haudenosaunee and the Wendat peoples and now home to many diverse First Nations, Inuit, and Métis. We also acknowledge that Toronto is covered by Treaty 13 with the Mississaugas of the Credit.About AlloyAlloy helps solve the identity risk problem for companies that offer financial products. Over 600 banks, credit unions, and fintechs turn to Alloy’s end-to-end identity risk management platform to take control of fraud, credit, and compliance risks, and grow with confidence. Founded in 2015, Alloy is powering the delivery of great financial products to more customers around the world. Learn more at alloy.com.
NEW YORK, August 21, 2024 -- Alloy, the identity risk management company trusted by over 600 leading banks, credit unions and fintech companies, today released its 2024 State of Embedded Finance Report, a survey of over 50 decision-makers working at U.S.-based sponsor banks. The report found that while embedded finance programs drive significant revenue (over 50%) for sponsor banks, a majority (80%) of respondents reported that meeting embedded finance compliance requirements as a sponsor bank is challenging in the current environment. Alloy’s State of Embedded Finance Report comes at a time when sponsor banks in the U.S. face drastically increased regulatory scrutiny. According to data from Klaros Group, 25.6% of the FDIC’s formal enforcement actions have been directed at sponsor banks since the beginning of 2024. “Running a sponsor bank program is inherently complex because you have banks who are highly regulated working with companies that are often new, fast-growing, and creating entirely new ways for consumers to interact with money,” said Tommy Nicholas, CEO and co-founder of Alloy. “Despite the challenge, we’re already seeing sponsor banks respond to regulatory developments by investing in better controls, training, and adding to their compliance tech stack.”These recent compliance violations have resulted in financial consequences for sponsor banks: Alloy’s report found that 75% of sponsor banks have lost $100k or more due to compliance violations, with 39% reporting losses of $250K or more and 6% reporting losses of $1M or more. However, financial losses are far from the worst consequence of regulatory violations: decision-makers at sponsor banks rank reputational damage as the top consequence of mishandling fintech partners’ compliance. Alloy’s report found that sponsor banks’ top barriers to maintaining a compliant embedded finance program are 1) a lack of control over their fintech partners’ policy controls and 2) a lack of auditability of their fintech partners’ policy controls. Earlier this year, Alloy launched Alloy for Embedded Finance, a product that gives sponsor banks, electronic money institutions, and program managers in the U.S., U.K., and E.U. the ability to oversee the compliance policies of their fintech partners. Alloy for Embedded Finance directly addresses embedded finance providers’ need to have greater control and visibility into their fintech partners’ compliance programs. Today, Alloy also announced a new module within Alloy for Embedded Finance: Audit Access. Tools like Alloy for Embedded Finance are becoming more widely adopted by sponsor banks: Alloy’s report found that sponsor banks’ most likely course of action in response to regulatory scrutiny is investing in new compliance technology. “Using Alloy for Embedded Finance has been a game changer for our team,” said Teddy Gordon, Director of Data at Grasshopper Bank. “We can easily set KYC requirements for our fintech partners and then roll those policies out to our entire program all at once. We ensure we’re compliant across the board, and our fintech partners still get to manage their own risk tolerance.”Alloy’s State of Embedded Finance report was fielded from May 30th to June 5th, 2024 and includes respondents from sponsor banks in the U.S. with at least $2 billion assets under management (AUM). The report was conducted on behalf of Alloy by The Harris Poll, a global consulting and market research firm.For more insights, read the full report here. About AlloyAlloy solves the identity risk problem for companies that offer financial products. Over 600 banks, credit unions, and fintechs turn to Alloy’s end-to-end identity risk management platform to take control of fraud, credit, and compliance risks, and grow with confidence. Founded in 2015, Alloy is powering the delivery of great financial products to more customers around the world. Learn more at alloy.com.
NEW YORK, July 2, 2024 -- Alloy, the identity risk management platform for companies that offer financial products, announced that Kathryn Cook has joined the company as its new Chief Marketing Officer (CMO) to support the company’s rapid, global growth. Cook joins the company following nine years at nCino (NASDAQ: NCNO), an Alloy partner and leader in cloud banking for the financial services industry. While at nCino, she helped lead the company’s global marketing and communications functions as it grew from an upstart to a leading provider of banking solutions and a publicly traded company. “Over the last few years, Alloy has grown in almost every way possible. We’ve expanded globally, added capabilities with new products, extended both our reach and the strength of our network through strategic partnerships, and seen significant client adoption across banking and fintech,” said Tommy Nicholas, Co-founder and CEO of Alloy. “But in my eyes, we are only just getting started. I couldn’t be more thrilled to welcome Kathryn to the Alloy team as our first CMO and partner with her as we enter our next phase of growth.”Founded in 2015, Alloy is trusted to solve the identity risk problem for over 600 of the world’s top financial services companies, including Stash, Live Oak Bank, Grasshopper Bank, Ally, M&T, Carta, Ramp, and Shopify.Alloy has grown extensively over the last year, adding new solutions, partners, and clients. Recent highlights include: Added over 200 new clients, including 12 of the top 50 U.S. banks; Expanded presence in the U.K. with new hires, clients, and triple-digit revenue growth since launching in the U.K. market in 2022;Saw strong double-digit growth bolstered by newly launched solutions including Ongoing Fraud Monitoring and Alloy for Embedded Finance;Deployed over 50 new data product integrations across more than 30 partners to help clients stay ahead of the pace of fraud, with access to an ecosystem of over 200 data integrations. New partners include Enigma, Quantifind, and TrueBiz; Continued to add new technology partners including Lumin Digital and Origence; Alloy is also integrated with nCino, Narmi, MANTL, Apiture, Prelim, Baker Hill, Blend, and Treasury Prime. “Over the last nine years, Alloy has established itself as a leader in identity risk and fraud prevention solutions for innovative fintechs and financial institutions through its best-in-class products, people, and partnerships,” said Cook. “The pace of fraud continues to increase, and I believe Alloy has a massive opportunity to help organizations of all sizes, worldwide, fight fraud, manage compliance risks, and grow with confidence. I am thrilled to be joining the company at this exciting point in its trajectory, and I look forward to helping further advance Alloy’s bold mission and accelerate its growth.” About AlloyAlloy solves the identity risk problem for companies that offer financial products. Today, over 600 banks and fintechs turn to Alloy’s end-to-end identity risk management platform to take control of fraud, credit, and compliance risk, and grow with confidence. Founded in 2015, Alloy is powering the delivery of great financial products to more customers around the world. Learn more at alloy.com.
Alloy helps Earnest optimize customer onboarding and underwriting to boost conversion rates
NEW YORK, February 29, 2024 -- Alloy, the identity risk management company behind nearly 600 leading banks and fintech companies, today announced Alloy for Embedded Finance, a new product custom-designed for sponsor banks, BaaS providers, and their fintech partners to collaboratively manage identity risk and stay ahead of regulatory requirements.Oftentimes, sponsor banks have not had sufficient oversight or control over whether their fintech partners have adhered to the banks’ government-mandated compliance requirements. Alternatively, in models where sponsor banks have taken on all compliance responsibilities, they have often forced their fintech partners into a one-size-fits-all approach to compliance that doesn’t suit fintechs’ evolving risk needs and often adds unnecessary friction to their user experiences.Alloy for Embedded Finance solves these challenges. The new product leverages the strength of Alloy’s existing platform while introducing a new parent/child account configuration. Sponsor banks (or ‘parent accounts’) have the ability to designate different levels of autonomy and guardrails for each of their fintech partners (or ‘child accounts’), depending on how mature the fintech is, how much of the process the fintech wishes to own, and the risk appetites of both parties. With this construct, sponsor banks can seamlessly build compliance policies, then issue and enforce them to each of their fintech partners all at once. More mature or 'autonomous' fintechs can customize their controls on top of these baseline policies, giving them the flexibility to tailor risk measures that don't add unnecessary friction for end users. Regardless of the autonomy level a fintech partner has, their sponsor bank retains total oversight of their policies to ensure they are fully compliant.“Sponsor banks can't operate without controlling the CIP/KYC and AML/BSA policies of the fintechs in their program—recent enforcement actions make this clear,” said Tommy Nicholas, CEO and Co-founder at Alloy. “At the same time, risk programs that are ‘one size fits all’ result in terrible user experiences for fintechs that pride themselves on providing a frictionless interface. Alloy for Embedded Finance solves both sides of this problem.”Alloy for Embedded Finance arrives during a period of massive potential for the embedded finance industry: Ernst & Young predicts that the global embedded finance market across the entire value chain will grow to $606B by 2025. However, the industry has been plagued by compliance challenges, with regulators increasing pressure on sponsor banks to ensure their third-party partners meet compliance requirements. According to data from advisory firm Klaros Group, sponsor banks drew one-third of all formal enforcement orders by federal banking agencies in the fourth quarter of 2023. With regulatory attention unlikely to slow down, it is more critical than ever for sponsor banks and their fintech partners to work collaboratively to meet compliance requirements so they can truly capture the full potential of the embedded finance market. Alloy already works with many of the leading sponsor banks, BaaS providers, and fintechs in this space, including Grasshopper, Liberis, Treasury Prime, and Marqeta.Learn more about Alloy for Embedded Finance here.About AlloyAlloy solves the identity risk problem for companies that offer financial products. Today, nearly 600 banks and fintechs turn to Alloy’s end-to-end identity risk management platform to take control of fraud, credit, and compliance risks, and grow with confidence. Founded in 2015, Alloy is powering the delivery of great financial products to more customers around the world. Learn more at alloy.com.