Authentication failures are fraud prevention failures
When authentication and fraud prevention operate in silos, account takeover attacks slip through. Here's what unified detection actually looks like.
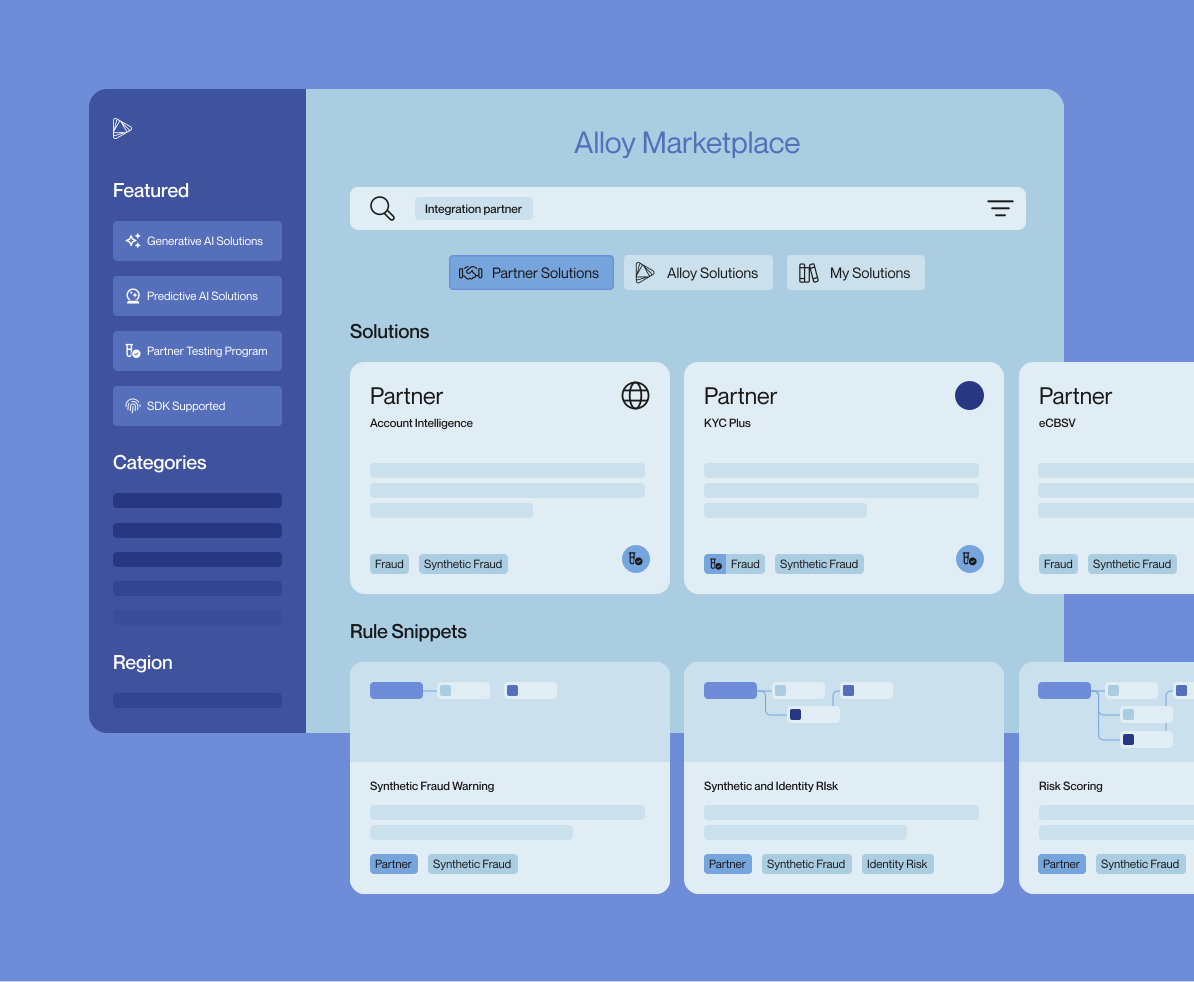
Alloy Marketplace unites 270+ partner solutions and a new library of pre-built decisioning logic in one dashboard. Discover, test, and deploy from one place.
Why spend time on tedious manual reviews when AI can do it for you? Learn how agentic AI for KYC and compliance is helping financial orgs optimize efficiency.
7th largest credit union in the U.S. drives growth by keeping members safe
Alloy’s real-time risk assessments helps IncredibleBank create a holistic risk profile for each applicant.
Alloy helps Earnest optimize customer onboarding and underwriting to boost conversion rates
Know Your Agent (KYA) is how financial institutions verify AI agents acting for customers. Learn the core controls and how it differs from KYC.
Learn how actionable AI empowers financial institutions and fintechs to move from detecting fraud to agile prevention.
Banks and fintechs run into challenges that cause customer friction when it comes to AML, KYB, and KYC regulations.
Embedded finance solutions can help banks maintain compliance control while giving fintechs the flexibility to customize their risk management approach.
London, UK, February 6, 2024 -- Liberis, the leading global embedded finance platform, today announced a partnership with Alloy, the identity risk management company behind over 500 of the world’s leading banks and fintechs. The partnership will enable Liberis to leverage Alloy’s platform to fast-track its global growth, and simplify the merchant experience by integrating automated compliance verifications into the funding application process. Additionally, it will facilitate the creation of custom, white-labelled onboarding experiences for partners. “We’re excited to partner with Alloy to help us achieve our global growth goals,” said Alexis Alexander, Chief Legal & Compliance Officer of Liberis. “Alloy’s platform will allow us to enter new markets quickly, optimise our merchants’ fully digitalised application for funding and scale to meet our partners’ demand, while also maintaining our high standards for compliance.” Alloy’s platform provides Liberis with access and integrations to a global network of over 190 data sources that help streamline KYC, KYB, and AML processes while also preventing financial crime. This will enable Liberis to onboard merchants in new markets quickly and efficiently. “We are thrilled to be partnering with Liberis to add them to our growing list of global clients,” said Tommy Nicholas, CEO at Alloy. “Alloy is designed to help businesses take control of fraud, credit, and compliance risk, while growing with the clearest picture of their customers. We’re confident that our partnership will help Liberis achieve its goals and provide its merchants with a seamless onboarding experience.” The collaboration between Liberis and Alloy will streamline the funding application process for merchants, minimising the paperwork involved. Most merchants will experience a smooth and seamless application process, with compliance verifications happening behind the scenes. In cases where further documentation is necessary, Liberis will offer a bespoke, white-label experience that aligns with the needs and standards of both merchants and their partners. “We hold ourselves to high standards on compliance, and we know it’s very important to our partners,” said Alexander. “But adding compliance checks can mean friction in the application journey. Using Alloy, we will be able to reduce this for most customers, whilst never compromising on a fully compliant process”. Liberis is committed to growing in a scalable way. By partnering with Alloy, Liberis can reduce the engineering resources required to support its international expansion and meet its compliance requirements. This allows Liberis to focus resources on its core mission of providing merchants with the funding they need to grow and thrive through their partners. About Liberis Liberis builds flexible embedded finance solutions that empower businesses and provide positive impact. Founded in 2007, Liberis is a leading global embedded finance platform with a mission to provide small businesses with accessible and responsible finance, based on the belief that funding should always be a positive force for small businesses. Liberis provides partners with the technology platform and financial solutions to offer hyper-personalised and accessible funding, empowering their small business customers to grow their revenues. With over 20 global strategic partners and direct reach to more than 1 million small businesses, Liberis has provided over $1bn of funding in over 60,000 transactions, enabling over 100,000 jobs to be created and saved. About Alloy Alloy solves the identity risk problem for companies that offer financial products. Over 500 banks and fintechs turn to Alloy’s end-to-end identity risk management platform to take control of fraud, credit, and compliance risks, and grow with confidence. Founded in 2015, Alloy is powering the delivery of great financial products to more customers around the world. Learn more at alloy.com.
NEW YORK, January 25, 2024 -- Alloy, the identity risk management company behind over 500 leading banks and fintech companies, today released its 2024 State of Fraud Benchmark Report, finding that after years of steadily increasing fraud rates, the number of reported fraud attacks have begun to even out – and for some organizations, to decelerate. Despite that progress, fraud has still resulted in significant financial losses: 56% of respondents lost more than 500,000 (EUR/USD) to fraud in the last 12 months, and 25% lost over 1M (EUR/USD) in that time. Alloy’s State of Fraud Benchmark Report tracks shifting trends in financial fraud, based on a survey of over 450 fraud decision-makers working at banks, credit unions, and fintechs in the US and UK. The report offers an inside look at how companies prepare for, experience and respond to fraud, and how that fraud translates to direct financial losses. This year’s report revealed a drop in the number of companies that have experienced 1,000 or more fraud attempts over the past year: In 2023, 35% of companies experienced 1,000+ fraud attempts, down from 47% in 2022. But it’s not all good news: 61% of companies saw an increase in attempted fraud attacks committed through consumer accounts in the past year, and 54% saw an increase in attempted fraud attacks committed through business accounts. “It’s encouraging to see companies getting fraud volume under control using the wide array of identity data and technology available on the market,” said Tommy Nicholas, CEO and co-founder at Alloy. “But fraud remains a critical problem because bad actors are always finding new tools—such as generative AI—to steal increasingly large amounts of money.” On the bright side, business sectors investing in the implementation of new fraud tools were more likely to see decreased fraud attempts last year. 24% of enterprise fintechs and 43% of mid-market banks said fraud attacks by consumer and business accounts decreased at their organizations in 2023. At the same time, 37% of enterprise fintechs and 60% of mid-market banks said they were investing in the implementation of new fraud tools, suggesting that their use of outside technologies may be helping to diminish their fraud volumes. In 2024, more companies are poised to continue their investments in fraud prevention solutions: 75% of companies across all sectors said they plan to invest in an identity risk solution in the next year. Though identity solutions are helping companies make progress in the fight against fraud, certain types of financial crime continue to plague companies. Businesses across the US and the UK ranked authorized push-payment (APP) fraud as their top fraud driver last year by case volume and losses. Looking ahead, US/UK companies ranked AI-driven fraud (24%) as the type of fraud they are most concerned about in 2024. With both APP fraud and AI-driven fraud frequently resulting from scams targeted at individual consumers, many US/UK companies (53%) also plan to invest in anti-scam education tools over the next year. Alloy’s report was fielded in November 2023 and includes respondents from growth fintechs (1-100 employees), strategic fintechs (101-500 employees), mid-market fintechs (501-100 employees), enterprise fintechs (1000+ employees), regional banks (<$10M AUM), mid-market banks ($10B - $50B AUM), enterprise banks (>$50B AUM), credit unions/community banks, and online/pure play lending institutions. The report was conducted on behalf of Alloy by Qualtrics, a leading survey platform that powers more than one billion surveys every year. For more insights, read the full report here. About Alloy Alloy solves the identity risk problem for companies that offer financial products. Today, over 500 banks and fintechs turn to Alloy’s end-to-end identity risk management platform to take control of fraud, credit, and compliance risks, and grow with confidence. Founded in 2015, Alloy is powering the delivery of great financial products to more customers around the world. Learn more at alloy.com.
We examine some highlights from 2023 and break down Alloy's year by the numbers.
Kyle Caldwell, Senior Vice President of Fraud Product Development at M&T Bank, discusses exploring Identity Verification vendors, striking the tricky balance of risk management alongside positive customer experiences, and how taking big risks in his personal life has paid off.
NEW YORK, Nov. 30, 2023 — Narmi, a leading provider of digital banking solutions, today announced an integration with NeuroID, the leader in fraud detection through behavioral analytics. Facilitated by joint partner Alloy, the identity risk management company, the NeuroID solution marks a pivotal step in Narmi’s fight against fraud. The partnership will empower mutual clients leveraging the Alloy platform to use real-time behavioral insights that will revolutionize their approach to fraud prevention. NeuroID's technology tracks and analyzes an applicant's unique behavior during the account opening process, providing a valuable additional layer of data for fraud detection in Alloy and streamlining the user experience for legitimate customers. Jack Alton, CEO of NeuroID, said, “NeuroID is thrilled to integrate with Narmi via the Alloy platform. This partnership will give community and regional financial institutions access to an untapped suite of top-of-funnel digital insights that are critical to evolving fraud prevention efforts. Tracking digital behavior allows financial institutions to decipher between bad actors, bots, and fraud rings, and fast-track legitimate opportunities with precision and speed.” With almost five years of partnership, Narmi and Alloy continue to work to deliver impressive results for community and regional financial institutions. Financial institutions currently utilizing NeuroID via Alloy have seen reductions in fraudulent applications as high as 35%, showcasing the strength of the technology. The integration occurs seamlessly on the back end, demonstrating Narmi’s commitment to delivering an account opening experience that prevents fraud without sacrificing user experience. “Fraud is constantly evolving. As a custodian of Account Opening solutions to financial institutions, it's our responsibility to continue to advance our fraud and risk offerings so banks and credit unions can remain safe and protected,” said Edwin Akrong, VP of Product at Narmi. “Narmi is dedicated to ensuring that our customers always have the most effective fraud prevention tools.” Brian Bender, Vice President of Strategic Alliances at Alloy added, “Fraud is an increasingly growing and complex challenge so we are thrilled to bring NeuroID to Narmi’s current and future customers.” About Narmi New York City-based Narmi's digital platform empowers financial institutions to unlock the very latest capabilities in digital banking and account opening, enabling them to move faster, tap new growth opportunities, and achieve true digital transformation. The Narmi platform was built with the customer experience in mind, empowering financial institutions with an experience that is always effortless, current, and dependable. As a result, Narmi's customers are seeing as much as 3x account growth in less than 30 days and 4x deposit growth in as little as 90 days. Additionally, Narmi's financial institution clients are winning awards like Bankrate's 2020 Best Online Bank and Nerdwallet's Best Bank of 2021 for Online Experience. For more information, please visit www.narmi.com. About NeuroID NeuroID, the global leader in behavioral analytics, offers a friction-free, privacy-centered, and tailored solution to digital identity screening. After more than a decade of researching human-online interactions, our solutions provide a front line of defense by differentiating between genuine users and potential threats in real time. NeuroID solutions assess a user's intent—be it a genuine prospect, fraudster, or bot—by analyzing their interactions with a digital device. Our unique crowd-level insights, paired with expert guidance support modern risk management so global leaders can see fraud faster, reduce losses, and increase savings. Learn more at https://www.neuro-id.com/. About Alloy Alloy solves the identity risk problem for companies that offer financial products. Over 500 banks and fintechs turn to Alloy’s end-to-end identity risk management platform to take control of fraud, credit, and compliance risks, and grow with confidence. Founded in 2015, Alloy is powering the delivery of great financial products to more customers around the world. Learn more at alloy.com.
Take a dynamic approach to customer retention. With Alloy Ongoing Monitoring, you can remarket to your existing customers and extend highly personalized credit offerings.
NEW YORK, Oct. 18, 2023 -- Alloy, the identity risk management company, is expanding its credit underwriting capabilities to support banks, fintechs, and other builders of financial products in managing their holistic credit risk. In a challenging macro-environment, Alloy enables lenders to make smarter credit decisions, capture default risk, and increase revenue by identifying upsell and cross-sell opportunities. Alloy also automates credit line management and product remarketing, helping lenders maintain appropriate credit limits and proactively extend new product offers to customers. Lenders rely on Alloy’s established credit underwriting capabilities to offer credit products to more people with less risk. Alloy allows lenders to automate their credit decisions using identity data gathered during onboarding, credit bureau data, and alternative underwriting data. Lenders can make credit decisions using custom models, building anything from basic workflows to complex matrix models right within Alloy. Alloy’s updated credit offering builds upon these existing capabilities to offer a comprehensive and proactive approach to credit management beyond origination, enabling banks and fintechs to monitor for credit risk throughout the customer lifecycle. New features include: Automated, scheduled checks using the richest set of credit signals to monitor the ongoing financial health of borrowers: Lenders can incorporate fresh data pulls into their decisioning from a wide range of third party data sources: including credit bureau data, alternative underwriting data, and their own proprietary data. This comprehensive approach enables lenders to build a more complete picture of a borrower's creditworthiness and potential risks and carry out more data-driven decisions.Real-time alerts sent to lenders to notify them about changes in a borrower’s risk (e.g. if a borrower declares bankruptcy): Lenders can then take proactive measures to prevent the accumulation of high-risk loans.Automated line management: Lenders can maintain appropriate credit limits and terms through continuous monitoring to determine if customers qualify for a credit line change based on behavior and automatically conduct line adjustments.Automated credit remarketing process: Lenders can monitor positive customer behaviors like timely repayments and salary increases and can offer good customers new products, ultimately increasing their company revenue. “Historically, lenders have had to rely on point-in-time, siloed information about their borrowers,” said Parilee Wang, Chief Product Officer at Alloy. “With Alloy, lenders have a holistic solution for building a more complete picture of a borrower's ongoing creditworthiness and potential risks.” Alloy’s product investment in the credit space comes as U.S. consumer credit card debt has topped $1 trillion for the first time in history. As many borrowers face increased financial strain impacting their ability to repay debts, lenders may be forced to make difficult decisions about the creditworthiness of their applicants. At the same time, as revolving credit usage grows and consumers demand personalized, seamless experiences from their financial institutions, lenders are challenged with remaining top of wallet and staying ahead of competitors. “We were so excited to find a credit underwriting solution that lets us proactively manage our credit risk and allows us to rely on automated decisioning,” said Bobby Parker, Head of Credit at PEX Card. “The configurable platform allows us to be nimble, and we can make critical underwriting changes quickly with the appropriate controls in place. Furthermore, with the A/B test feature, and pre-built integrations with salient data providers, we can ensure our decisions are driven by data and information gain. Leaning on this solution will give us the ability to prudently grow our portfolio while driving strong risk adjusted returns.” Alloy offers the broadest coverage of third-party data in the industry with more than 190 data sources, including credit bureaus and alternative credit data providers. Some of Alloy’s partners in the credit space include: EquifaxExperianTransunionNova CreditFISZest AIPrism DataInscribeCodat About Alloy Alloy solves the identity risk problem for companies that offer financial products. Today, nearly 500 banks and fintechs turn to Alloy’s end-to-end identity risk management platform to take control of fraud, credit, and compliance risk, and grow with confidence. Founded in 2015, Alloy is powering the delivery of great financial products to more customers around the world. Learn more at alloy.com.
As Hispanic Heritage Month comes to a close, Lianna Santiago — Manager of Alloy's Implementations Team — reflects on what it's like being a Latina in tech and shares how Alloy's Hispanic/Latine employee resource group celebrated the month.
We chat with Rachel Sapers, Carta's Vice President and Chief Compliance Officer for AML, on how they came to work in risk management, their role at Carta, and their views on the role of risk management in driving business growth.
Alloy Onboarding and NeuroID help Jovia refine their strategic approach to stopping fraud surges
As we get ready for this year's Women in Fintech Money20/20 event, we caught up with some prominent women in fintech who will be attending the event to learn about their experiences and ask them what they are excited about this year at the event.
What started as a simple piece of technology has evolved to help banks and fintechs stay ahead of ever-changing fraud risks.
Alloy Onboarding helps Elements meet member expectations and stop more fraud at origination.
Our Employee Experience Manager, Ted Lord, breaks down what makes Alloy's culture unique.
NEW YORK, Aug. 15, 2023 -- Alloy, the identity risk management company, today released a report that found 60% of fintechs surveyed report paying at least $250,000 in compliance fines, with one-third paying over $500,000. The report also found larger fintechs were more likely to report higher compliance fines—37% of fintechs with 1,000+ employees reported paying over $500K in compliance fines last year. The State of Compliance Benchmark Report surveyed over 200 compliance decision-makers working at financial technology companies in the U.S. The survey ran from June 6-12, 2023, and included respondents from small (1-500 employees), medium (501-1000 employees) and large (1000+ employees) organizations. The report was conducted on behalf of Alloy by Qualtrics, a leading survey platform that powers +1B surveys every year. Nearly all fintechs (93%) reported that bank secrecy act (BSA) compliance requirements—including anti-money laundering (AML) and know your customer (KYC) requirements—were challenging to meet. Even so, most fintechs (80%) are doing more than the minimum amount of risk management required to meet these compliance requirements—suggesting a robust compliance program requires labor beyond even what is mandated by the U.S. government. "Because fintechs enable people to manage their money and make financial decisions, there's no wiggle room when it comes to compliance," said Gizelle Barany, General Counsel at Alloy. "In addition, the pace of bad actors is often faster than regulators are able to keep up with, so it's not surprising that many fintechs are doing more than the minimum to prevent financial crime." When it comes to the consequences of mismanaging compliance, while fintechs are concerned with fines, they are even more concerned about customer confidence in their ability to properly handle operations. According to 34% of fintechs, customer confidence had the greatest impact on their BSA compliance decisions, followed by reputational damage at 25%. Under the Bank Secrecy Act (BSA), financial institutions are required to assist U.S. government agencies in detecting and preventing money laundering, and report suspicious activity that might signal criminal activity (e.g., money laundering, tax evasion or human trafficking). Writing and filing suspicious activity reports (SARs), suspicious transaction reports (STRs), and currency transaction reports (CTRs) is a key part of compliance professionals' responsibilities, with 34% ranking it as the most time-consuming part of their work. More than one-third (36%) of fintechs filed anywhere from 5-10k SARs per year, with large organizations more likely to file 10-50k SARs. No matter an organization's size, SAR writing and filing is time-consuming: 25% of fintechs said that filing a SAR takes 1-2 weeks. For more insights, read the full report here. About Alloy Alloy solves the identity risk problem for companies that offer financial products. Today, nearly 500 banks and fintechs turn to Alloy's end-to-end identity risk management platform to take control of fraud, credit, and compliance risks, and grow with confidence. Founded in 2015, Alloy is powering the delivery of great financial products to more customers around the world. Learn more at alloy.com.
One of the leaders of Alloy's LGBTQ+ employee resource group (ERG), Ariana Longoria, reflects on her experience as a lesbian employee at Alloy and shares how Alloy celebrates Pride yearlong.
SAN FRANCISCO, June 13, 2023 -- Astra, a leading provider of infrastructure for faster payments, today announced a partnership with Alloy, the identity risk management company, to streamline the onboarding process for existing Alloy customers to leverage Astra’s advanced transfer technology in their applications. “Astra and Alloy both aim to make the business of building fintech products and integrating faster, secure payments easier. By working together, we can improve the overall developer experience and help enterprises accelerate their time to market,” said Gil Akos, CEO and co-founder of Astra. “With Alloy’s identity risk solutions, businesses can confidently onboard verified customers. Paired with Astra’s best-in-class payment technology, more product owners and consumers can leverage accelerated settlement of funds.” Debit transfers are a convenient and secure way for businesses to send money to their customers. Yet, many organizations face overwhelming and unnecessary complexities in successfully facilitating them. With Astra’s platform, businesses can effortlessly create and send debit transfers to their customers’ bank accounts. Astra also offers a variety of features that make it simple for businesses to manage the lifecycle of payments, including a dashboard where they can track payment status and monitor transfer activity. “We’re thrilled to partner with Astra to help businesses offer faster payments,” said Brian Bender, VP of Strategic Alliances at Alloy. “Alloy’s identity risk management platform will help businesses quickly and safely onboard genuine customers and start offering debit transfers, without taking on additional risk.” As a result of this partnership, more businesses can now offer debit transfers and Visa Direct payments, improving customer experience and the growth of their business by freeing up critical developer time and resources. About Astra Astra offers advanced payment infrastructure, powering faster transfers for fintech products, financial institutions, and enterprises. Astra’s proprietary, vertically-integrated API enables developers to offer instant payments and accelerated bank transfers, with built-in optimizations to reduce risk. For more information, visit https://astrafi.com About Alloy Alloy solves the identity risk problem for companies that offer financial products. Today, nearly 500 banks and fintechs turn to Alloy’s end-to-end identity risk management platform to take control of fraud, credit, and compliance risk, and grow with confidence. Founded in 2015, Alloy is powering the delivery of great financial products to more customers around the world. Learn more at alloy.com.
May marked Asian American & Pacific Islander (AAPI) Heritage Month. AAPI @ Alloy did not disappoint by planning some special programming to help the Alloy community celebrate.
Another month, another set of excellent events from Alloy’s Employee Resource Groups (ERGs)! Trail Blazers (our ERG for women @ Alloy) hosted a panel with Women in Fintech and a volunteer event. HOLA (our Hispanic Organization & Leadership ERG) hosted a spicy salsa social. Meanwhile, the DEI Committee is hard at work behind the scenes planning company-wide training programs for the rest of the year.
NEW YORK, March 21, 2023 -- Alloy, the leading Identity Decisioning Platform for banks and fintech companies, today announced its partnership with Kyckr, a corporate KYC company providing businesses with real-time data on prospective and existing customers and suppliers. The partnership gives Alloy’s 350+ clients — including Carta, Ramp, and Brex — a powerful tool in performing Know Your Business (KYB) for companies outside of the US. "With fraud higher than ever before, finding a speedy but safe way to onboard business customers remains a challenge for many financial institutions, particularly as they look to service clients in multiple global markets," said Edwina Johnson, Head of Global at Alloy. "Integrating Kyckr into Alloy’s platform will help our clients provide a seamless digital onboarding experience to customers without increasing the risk of fraud, no matter where in the world they are located." This partnership with Kyckr comes on the heels of Alloy’s UK launch in February, in which it strengthened its presence in EMEA with key senior hires and office space in London. Alloy first expanded to 40 new countries in 2022. Today, over 350 companies around the world use Alloy’s API-based platform to connect to more than 170 data sources, automate identity decisions during account origination, monitor them on an ongoing basis, and make credit underwriting decisions. Kyckr provides real-time access to aggregated corporate Know Your Customer (KYC) and Ultimate Beneficial Owner (UBO) data from over 300 company registries and primary regulated sources worldwide, helping organisations to avoid the significant regulatory and commercial costs associated with using poor-quality data. The partnership will strengthen Alloy’s ability to help financial institutions overcome the challenges of achieving seamless digital business onboarding on an international basis. “Tackling financial crime is the number one priority and it can only be achieved if companies can identify the criminals and meet the increasing scrutiny of regulators,” said Ian Henderson, CEO of Kyckr. “Our partnership with Alloy means its customers can automatically validate the status of companies at the respective corporate register in real-time, helping avoid the significant regulatory and commercial risks associated with using poor quality data.” To learn more about Alloy, visit https://www.alloy.com About Alloy Alloy helps over 350 banks and fintech companies make safe and seamless fraud, credit, and compliance decisions. Founded in 2015 and backed by leading investors from Lightspeed Venture Partners, Bessemer Venture Partners, and Canapi Ventures, Alloy’s platform connects companies to more than 170 data sources of KYC/KYB, AML, credit, and compliance data through a single API to help create a future without fraud. Learn more at https://www.alloy.com. About Kyckr Kyckr is a B2B information services company that aggregates, organises and structures the world’s primary source company data to help businesses reduce the risks associated with counterparty relationships. Unlike traditional data companies which source data from multiple, secondary sources, Kyckr provides accurate data with trusted, legally-authoritative provenance. This helps organisations to avoid the significant regulatory and commercial costs associated with using poor-quality data. Through the combination of accurate data with innovative technology, Kyckr’s solutions help businesses to succeed in the fight against fraud, money laundering and financial crime. Kyckr is wholly owned by serial entrepreneur and founder of WiseTech Richard White through his personal investment vehicle RealWise KYK AV Pty Ltd. Learn more at https://www.kyckr.com/.
Our employee resource groups (ERGs) hosted some amazing events over the past month, and our employees celebrated Black History Month and Women’s History Month.
CARMEL, Ind., Feb. 28, 2023 -- Baker Hill, a leading financial technology provider in delivering solutions for loan origination, risk management and analytics, has partnered with Alloy, an identity decisioning platform, to help financial institutions verify more prospective borrowers digitally and ensure compliance throughout the loan origination process. Through the partnership, financial institutions using Baker Hill NextGen® can now leverage Alloy Onboarding, which features a single-API identity decisioning platform, connecting multiple data sources into customized workflows during account origination. As a result, banks and credit unions can verify prospective borrowers quickly and accurately with fewer manual reviews and less fraud while complying with KYC and AML requirements. With integrations to more than 170 data sources, Alloy also gives Baker Hill's financial institution clients more flexibility to use the fraud prevention and identity solutions they prefer in their loan origination workflows. Additionally, Alloy makes it easy to incorporate new data sources or adjust workflows, eliminating the need for community financial institutions to rely on coding or costly programming to make changes. "There's been nearly a 7 percent increase in lending fraud among small and midsize businesses since 2020 and according to a 2021 report by Aite-Novarica Group, only 31 percent of lending institutions had negligible rates of fraud incidence," said Mike Horrocks, Vice President of Product Management at Baker Hill. "At the same time, many community banks and credit unions are focused on lending outside of their traditional markets to expand their reach, which can expose these institutions to added risk. By partnering with Alloy, Baker Hill helps minimize risk and time spent on manual reviews so financial institutions can generate loan growth with confidence, even in new markets." "For community financial institutions to remain competitive among borrowers, offering a seamless digital lending experience from day one is crucial," said Brian Bender, VP of Strategic Alliances at Alloy. "Together, Alloy and Baker Hill make it easier for banks and credit unions of all sizes to provide a world-class experience for borrowers while mitigating the risk of fraud and ensuring compliance. We are proud to work with an industry-leading fintech like Baker Hill and look forward to empowering their financial institution clients to accept more loan applicants without additional fraud risks." About AlloyAlloy helps over 360 banks and fintech companies make safe and seamless fraud, credit, and compliance decisions. Founded in 2015 and backed by leading investors from Lightspeed Venture Partners, Bessemer Venture Partners, and Canapi Ventures, Alloy's platform connects companies to more than 170 data sources of KYC/KYB, AML, credit, and compliance data through a single API to help create a future without fraud. Learn more at https://www.alloy.com. About Baker HillBaker Hill is in the business of evolving loan origination by combining expertise in technology with expertise in banking. Built on decades of walking alongside banks and credit unions as they provide vital resources to their communities, Baker Hill NextGen® is a configurable, single platform SaaS solution for commercial, small business, consumer loan origination, and risk management that grows along with you as your business needs change. Baker Hill is lending evolved. For more information, visit bakerhill.com.
Alloy's co-founder and CEO, Tommy Nicholas, reflects on the foundations that help inform everything we do here at Alloy.